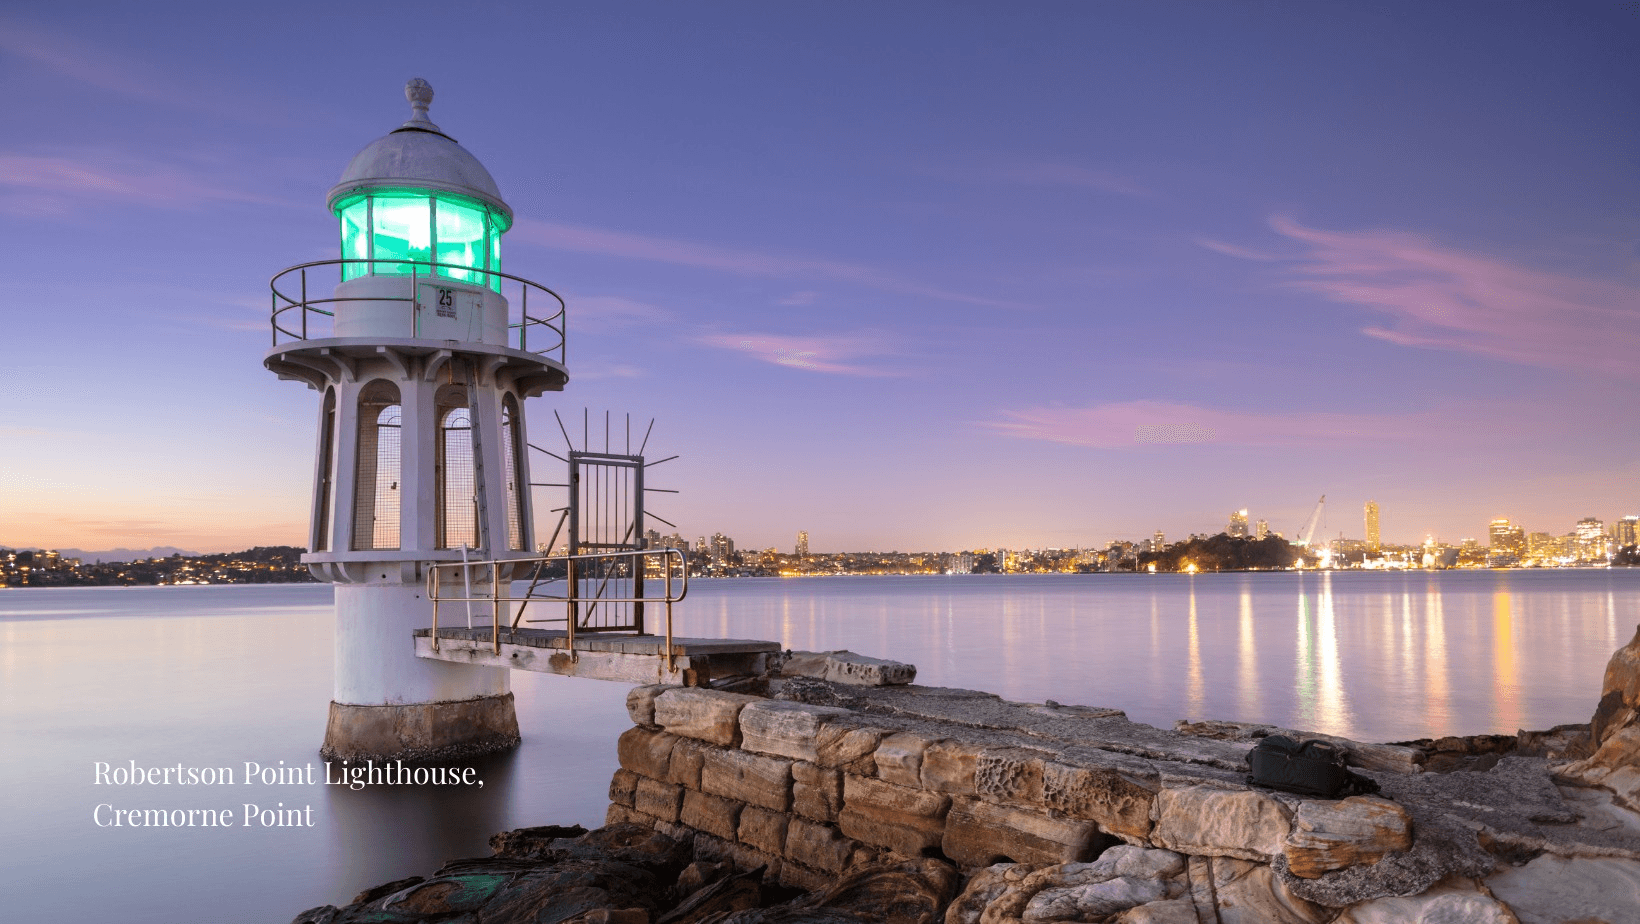
Robertson Point Lighthouse at Cremorne Point at dusk, with the city lights across the harbour

Cremorne, Lower North Shore

Mortgage Broker in Cremorne

Cremorne is where a lot of Lower North Shore buyers start: a first apartment off Military Road, then a semi or house when the family grows. Each step runs on different lender rules, from first home buyer schemes to how rent from your old unit is counted, and that's where comparing lenders makes the biggest difference.

Lower North Shore local · 40+ lenders · MFAA Approved Broker

Reviewed by Will Kiln, Principal Broker · Updated October 2026

  • MFAA Approved Broker
  • AFCA member 121049

We're local to Cremorne and compare 40+ lenders for first home buyers, upgraders and investors. Whether you're buying a one-bedroom near Cremorne Junction, moving your family into a semi, or holding onto your apartment as an investment when you upgrade, we match the loan to the lender that suits it.

Much of Cremorne is apartments, and lenders are pickier about apartments than houses. Building age, floor area, strata health and whether a government scheme applies all change the answer, so we check those before you apply.

Upgrading from your Cremorne apartment? Get a free estimate of what it could be worth.

Get my home value

Who we help in Cremorne

First home buyers

Buying a first apartment with a smaller deposit.

Example: a couple buying a $1.2m two-bedroom apartment with a 5% deposit and no lenders mortgage insurance under the Australian Government's 5% Deposit Scheme.

Growing families

Moving from a unit into a semi or house, in Cremorne or next door in Neutral Bay or Mosman.

Example: selling a two-bedroom apartment and using the equity as the deposit on a semi, with bridging finance if the sale and purchase dates don't line up.

Upgraders keeping their apartment

Holding onto your first apartment as an investment when you move.

Example: keeping a Cremorne one-bedroom as a rental and releasing equity from it towards the next home, so you don't have to sell.

Buying with family help

Family guarantees that use equity in the parents' home.

Example: parents guarantee part of a loan so their son can buy above the $1.5m first home scheme cap without lenders mortgage insurance.

Professionals

LMI waivers for eligible medical, legal and accounting professionals.

Example: a lawyer buying a Cremorne semi with a 10% deposit and no lenders mortgage insurance.

Investors

Buying, refinancing or restructuring investment apartments.

Example: refinancing an older investment loan on a Cremorne walk-up to a sharper rate and separating it cleanly from the home loan.

Examples are illustrative only, not client outcomes.

Will Kiln, Principal Broker at Cumulus Capital

Your Cremorne broker

Talk to the person who'll actually do your loan

I'm Will Kiln, Principal Broker at Cumulus Capital. I live on the Lower North Shore with my family and have spent more than 15 years in lending. When you call, you speak to me, from the first chat through to settlement and beyond.

Cremorne by home type

In Cremorne, the type of home you're buying shapes the loan more than the street does.

1960s–80s walk-up blocks

The homes

Red-brick walk-ups spread across Cremorne, mostly one and two bedrooms, many without lifts.

The lending angle

Lenders and valuers look at the building as well as the unit. Check strata minutes for special levies, waterproofing and concrete repairs before you exchange.

Military Road and Cremorne Junction

The homes

Apartments above shops and newer developments near the Orpheum and the bus corridor to the city.

The lending angle

Some lenders restrict shop-top and mixed-use buildings or apply lower maximum LVRs, so we check the building against lender policy early.

Studios and one-bedroom apartments

The homes

The entry point for many first home buyers.

The lending angle

Some lenders set minimum apartment sizes or limit LVRs on studios. A one-bedroom under $1m may also qualify for NSW first home buyer stamp duty relief.

Semis and townhouses

The homes

The usual step up for growing families, often on the streets either side of Military Road.

The lending angle

Some semis and townhouses sit on strata title rather than Torrens title, which can change lender policy and how the property is valued.

Federation and inter-war houses

The homes

Character houses on the quieter residential streets.

The lending angle

Heritage controls can apply, so renovation and rebuild plans need council approval before lenders release construction funds.

Lending in Cremorne: what to know

First home buyer schemes.

The Australian Government's 5% Deposit Scheme lets eligible first home buyers buy with a 5% deposit and no LMI on properties up to $1.5m in Sydney. NSW stamp duty relief is separate and stops at $1m.

Older strata blocks.

Check strata records for special levies and building works before you exchange. Lenders' valuers will look too.

Small apartments.

Some lenders have minimum apartment sizes or lower maximum LVRs for studios and very small units.

Keeping your unit as an investment.

Lenders usually count only part of the rent when assessing what you can borrow, and policies vary, so the right lender can be the difference between keeping the unit and selling it.

Cremorne home loan FAQs

It depends on your income, debts, deposit and the lender's policy. If you're keeping an existing apartment, how each lender counts its rent and loan can shift your borrowing capacity a lot. A free 15-minute call gives you a realistic range across lenders.

Talk to a Cremorne mortgage broker

Book a free 15-minute call, or leave your details and we'll call you back.

Book a free 15-min call

Or call us on 0478 766 615

We'll call you back within 24 hours during business days.