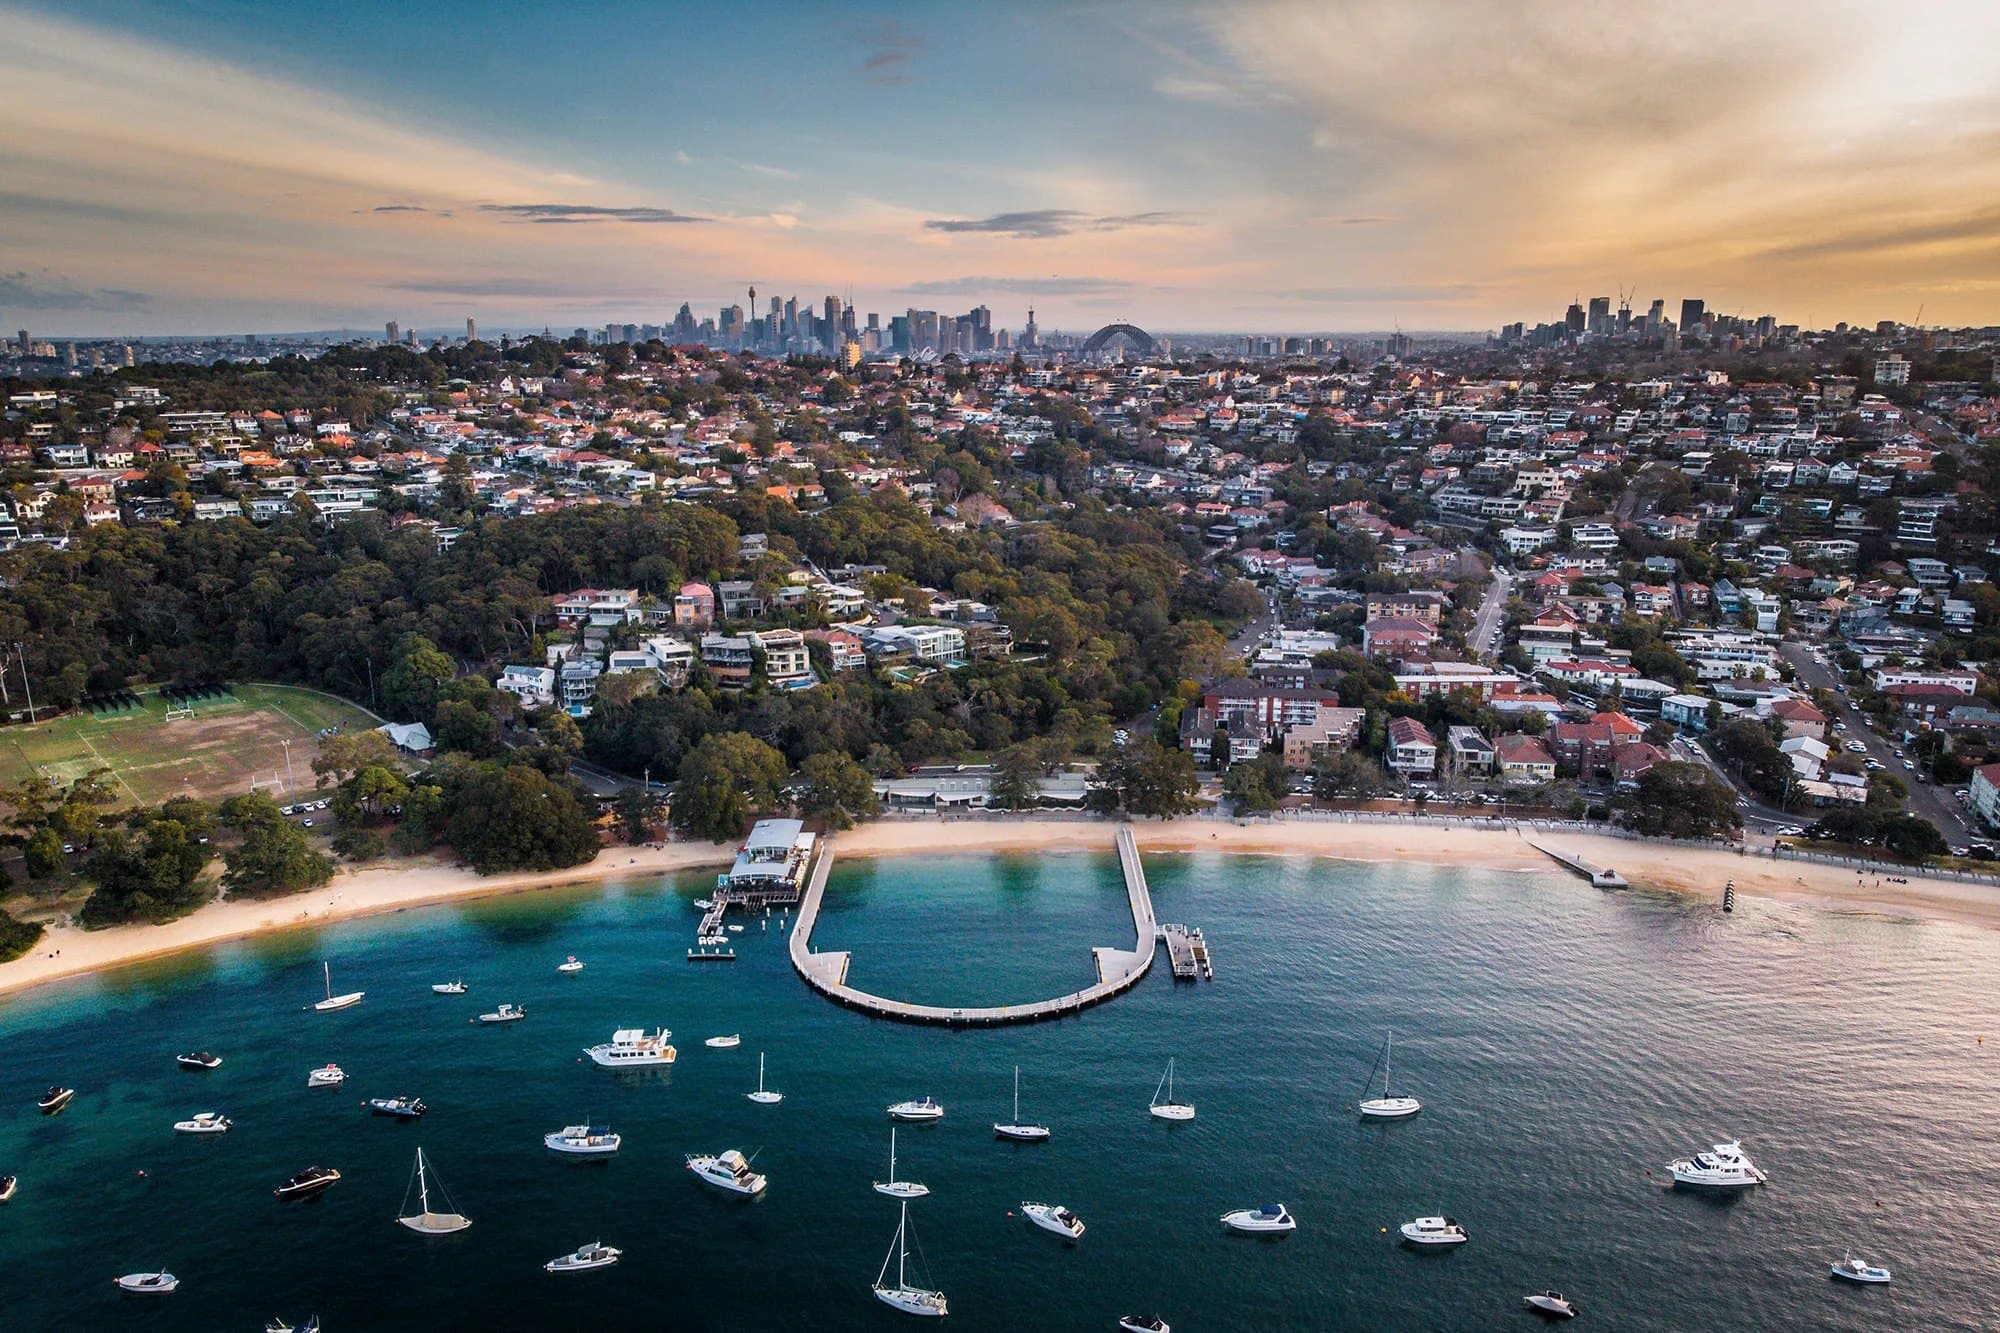
Aerial view of Balmoral Beach in Mosman at sunset, with the Sydney CBD and Harbour Bridge on the horizon

Mosman, Lower North Shore

Mortgage Broker in Mosman

Buying, upgrading or refinancing in Mosman usually means a large loan, and that changes which lenders want your business. Some cap loan-to-value ratios on bigger loans, some offer sharper private-banking pricing, and some assess bonus or business income far more generously than others.

Lower North Shore local · 40+ lenders · MFAA Approved Broker

Reviewed by Will Kiln, Principal Broker · Updated October 2026

  • MFAA Approved Broker
  • AFCA member 121049

We're local to Mosman and compare 40+ lenders to match your loan to the lender that suits it, whether you're moving up from a Cremorne apartment, buying your forever home near Balmoral or restructuring an investment portfolio.

At Mosman prices, the lender matters as much as the rate. Loan-size limits, how bonus and trust income is assessed, bridging terms and valuation policy all vary, and the wrong fit usually shows up late in the process. We sort that out before you apply.

Thinking of selling to upgrade or downsize? Get a free estimate of what your Mosman home could be worth.

Get my home value

Who we help in Mosman

Upgrading families

Moving from a unit or semi into a house, often buying before selling.

Example: a family with equity in a Cremorne apartment uses a bridging loan to buy a Mosman house, then sells the apartment within six months to bring the debt back down.

Executives and business owners

Income from bonuses, RSUs, trusts or company profits that needs a lender who counts it properly.

Example: two lenders can assess the same base-plus-bonus package very differently, and choosing the right one can change borrowing capacity materially.

Downsizers

Buying an apartment while selling the family home.

Example: securing an apartment near Military Road first, with a short-term loan covering the gap until the house settles.

Renovators and rebuilders

Construction and renovation loans for heritage-sensitive homes, with funds released in stages as the build progresses.

Example: a rebuild funded on the “as if complete” valuation once council approval is in place.

Parents helping children buy

Family guarantees that use equity in the family home so adult children can buy nearby.

Example: parents in Mosman guarantee part of a loan so their daughter can buy in Neutral Bay without lenders mortgage insurance.

Professionals and returning expats

LMI waivers for eligible professionals and lenders that accept foreign income.

Example: a doctor buying with a 10% deposit and no LMI, or an Australian returning from London with UK income.

Examples are illustrative only, not client outcomes.

Will Kiln, Principal Broker at Cumulus Capital, in Mosman

Your Mosman broker

Talk to the person who'll actually do your loan

I'm Will Kiln, Principal Broker at Cumulus Capital. I live on the Lower North Shore with my family and have spent more than 15 years in lending. When you call, you speak to me, from the first chat through to settlement and beyond.

Mosman by precinct

Mosman isn't one market. Housing stock, and what lenders care about, changes from street to street.

Balmoral

The homes

Beachside streets around Balmoral Beach and The Esplanade, with large family homes and a handful of apartment blocks, often well above the Mosman median.

The lending angle

Loan sizes where lender caps, maximum LVRs and private-banking pricing matter most.

Beauty Point and The Spit

The homes

Middle Harbour waterfront, steep blocks and one-off architectural homes.

The lending angle

Unusual, high-value properties are harder to value, so the choice of lender and valuer matters. Some lenders reduce their maximum LVR for these homes.

Mosman Bay and South Mosman

The homes

Harbourside pockets near the ferry wharves, with period homes and older apartment blocks.

The lending angle

For older blocks, strata records, special levies and planned building works need checking before you exchange.

Spit Junction and Military Road

The homes

Mosman's main commercial strip, with apartments, shop-top units and newer developments along the bus corridor.

The lending angle

Some lenders restrict very small units, studios and mixed-use buildings, so we check the building against lender policy early.

Clifton Gardens and Georges Heights

The homes

Quieter harbourside streets near Chowder Bay and Headland Park, with family homes and heritage character.

The lending angle

Heritage controls can shape renovation plans, so we check council constraints before arranging construction or renovation finance.

Lending in Mosman: what to know

Loan size limits.

Many lenders apply extra assessment or lower maximum LVRs above certain loan amounts. Picking the right lender up front avoids a late "no".

Bridging finance.

Most Mosman upgraders buy before they sell. Bridging loans let you carry both properties for a set period, but terms vary widely between lenders.

Heritage conservation areas.

Parts of Mosman have heritage controls that limit knockdowns and extensions. Lenders want council approval before funding construction.

Older strata blocks.

Check strata records for special levies and building works before you exchange. Lenders' valuers will look too.

Mosman home loan FAQs

It depends on your income, debts, deposit and the lender's policy. At Mosman price points, differences in how lenders treat bonuses, trust income and existing debts can shift borrowing capacity by several hundred thousand dollars. A free 15-minute call gives you a realistic range across lenders.

Talk to a Mosman mortgage broker

Book a free 15-minute call, or leave your details and we'll call you back.

Book a free 15-min call

Or call us on 0478 766 615

We'll call you back within 24 hours during business days.